

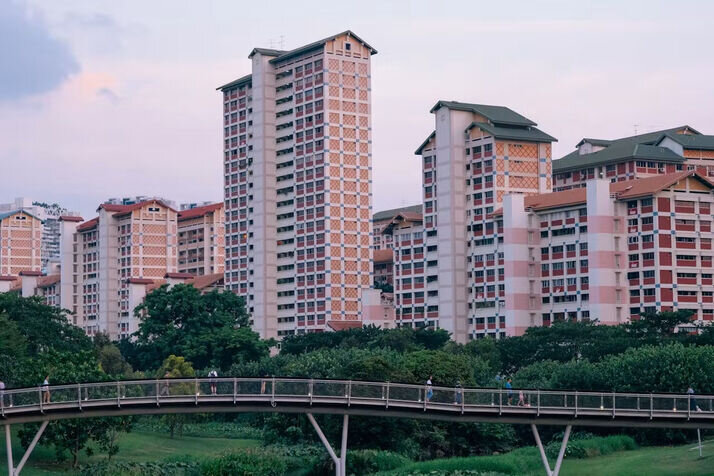
New Launch vs Resale Condo in Singapore 2026 Guide
A new-launch condo suits buyers who want a brand-new home and can wait for completion. A resale condo can suit buyers who need an existing home they can inspect and occupy sooner. Better value depends on the purchase price, usable space, lease, financing, condition, and ownership timeline.
When comparing a new launch v a resale condo in Singapore, start with the home you need and the money you can comfortably commit. A lower price per square foot does not automatically mean a better purchase. Neither does a developer discount.
This guide compares private condominiums, rather than executive condominiums, which have additional eligibility and ownership rules. We checked tax and financing references on 21 September 2026. All property examples below are hypothetical, not market averages or return forecasts.
What Is the Difference Between a New Launch and a Resale Condo?
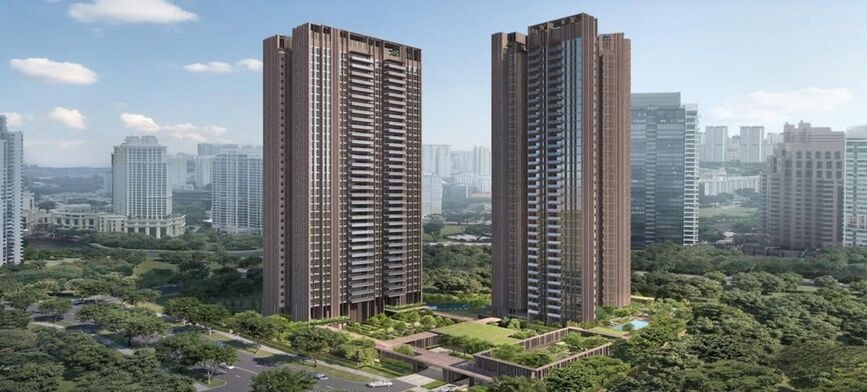
A new launch condo is marketed for first sale by a developer, often before construction finishes. Buyers assess the plans, specifications, location, and developer’s delivery record. Some developer-owned units remain available after completion, so a developer sale does not always involve a long wait.
A resale condo is purchased from an existing owner. For this comparison, resale means a completed unit; a transfer before completion is generally described as a subsale.
| Comparison | New launch condo under construction | Completed resale condo |
|---|---|---|
| Inspection | Plans, specifications and show flat | Actual unit and common areas |
| Moving timeline | Depends on completion and handover | Depends on sale completion, possession and renovation |
| Payment timing | Usually linked to construction progress | Balance generally due at sale completion |
| Condition | New finishes, with possible defects | Existing condition can be inspected |
| Lease | Check tenure and lease commencement | Check tenure and remaining lease |
| Rental evidence | Usually based on comparable projects | May include the development’s rental history |
| Main uncertainty | Completed result and delivery timing | Repairs, management and building condition |
How Should You Compare Condo Prices?
Compare similar units in similar locations before deciding whether either property is expensive. A city-center resale apartment and a suburban new launch serve different markets, even when both have two bedrooms.
Compare PSF and Total Purchase Price Together
Price per square foot, or PSF, equals the purchase price divided by the stated floor area.
Suppose a new launch costs S$1.8 million for 750 square feet. Its price is S$2,400 PSF. A resale unit priced at S$1.8 million for 1,000 square feet costs S$1,800 PSF.
Price disclaimer: These purchase prices and PSF figures are hypothetical illustrations, not Ziba Property listing prices or market averages. Actual prices vary by unit and date.
The resale unit provides more stated space for the same purchase price. However, the comparison remains incomplete until you examine the layout, lease, condition, floor level, and location.
Measure what matters to your household: bedroom dimensions, storage, kitchen space, and furniture placement. Large balconies or awkward corridors may contribute less to daily comfort than their area suggests.
For broader context, see our Singapore property market outlook, then compare evidence for the individual homes you shortlist.
Use Transactions, Not Only Asking Prices
Asking prices show what sellers hope to receive. Completed transactions show what buyers have paid. Provides private residential property information for purchase research. Select comparable transactions by location, tenure, size, building age, and sale date. Where possible, also account for floor and facing. Don’t let one unusually expensive sale determine your budget.
For a new launch, compare the developer’s price with nearby completed alternatives. Ask what the premium buys: a longer remaining lease, a better layout, different facilities, or simply newer finishes.
What Is the Total Cost of Buying Each Condo?
The total cost includes acquisition expenses, preparation costs, and ongoing ownership expenses. Separate these from cash-flow requirements: a mortgage principal repayment builds equity, although you still need money to make it.
Include stamp duties, legal fees, valuation charges, renovation, furnishings, mortgage interest, maintenance contributions, property tax, and insurance. Buyers waiting for construction may also need temporary accommodation.
Buyer’s Stamp Duty and ABSD
Buyer’s Stamp Duty (BSD) applies to both new launch and resale purchases. It is calculated on the higher of the purchase price or market value. Using the current residential bands, BSD on S$1.8 million is S$59,600, assuming the market value is no higher. Additional Buyer’s Stamp Duty (ABSD) depends on the buyer’s profile and property ownership, rather than whether the condo is new or resale. A Singapore citizen buying a first residential property generally has no ABSD; different profiles attract different treatment, and reliefs may apply. Confirm joint-purchase and remission conditions before committing.
For more context, read Ziba Property’s Singapore stamp-duty guide, alongside the current IRAS rules cited above.
Price disclaimer: The BSD amount above is an illustrative calculation, not a tax quotation. Confirm the applicable valuation, rates and buyer circumstances before purchase.
A Hypothetical Cost Comparison
| Selected cost | New launch | Resale |
|---|---|---|
| Purchase price | S$1,800,000 | S$1,800,000 |
| BSD | S$59,600 | S$59,600 |
| Assumed renovation and furnishing budget | S$30,000 | S$90,000 |
| Assumed temporary rent before moving | S$108,000 | S$9,000 |
| Subtotal of these items | S$1,997,600 | S$1,958,600 |
This illustration assumes temporary rent of S$3,000 monthly for 36 months versus three months. It excludes ABSD, financing, legal fees, and ongoing expenses. These are assumptions, not typical completion times or renovation quotes.
Price disclaimer: All amounts in this table and its accompanying graphic are hypothetical budgets, not current listing prices, quotations, or promised savings. Actual costs and tax liabilities vary.
The lesson is that accommodation costs can outweigh renovation savings. If you can remain in your present home without additional rent, the result changes. Replace every assumption with your own situation before comparing totals.
How Do Payment Schedules and Financing Differ?
For an incomplete developer sale, progressive payments generally follow construction milestones under the sale agreement. Loan disbursement and repayments develop accordingly. Confirm the exact schedule with your lawyer and lender.
A resale purchase concentrates the remaining purchase payment around completion. Arrange financing and the timing of any existing-home sale early.
Under the published bank-loan framework, eligible individuals with no outstanding housing loan may qualify for up to 75% loan-to-value financing, with a minimum 5% cash down payment. Lower limits can apply depending on age, tenure, and existing loans. The Total Debt Servicing Ratio threshold is generally 55%. These are limits, not guaranteed approvals.
For either option, test your budget against higher repayments and a temporary income interruption. Smaller early installments on a new launch should not disguise the eventual full mortgage commitment.
How Do Lease Length and Location Affect Value?
Compare tenure and remaining lease separately from building age. A newly completed leasehold condo does not necessarily start its land lease when you collect the keys. Check the actual commencement date.
For an older resale property, consider whether the remaining lease suits your intended ownership period. Obtain confirmation of financing and CPF eligibility for that specific unit. CPF use is subject to limits, so available account savings do not automatically equal usable purchase funds.
Freehold tenure is another comparison factor, not a guarantee of appreciation. A higher freehold purchase price still needs to make sense against the home’s condition and alternatives.
Location should be tested through actual journeys. Walk to the MRT entrance, time your commute, and visit nearby shops. Consider road noise, sheltered access, and your household’s daily routes.
Treat proposed infrastructure separately from facilities already operating. A future station may be relevant, but its delivery date and benefits should not be assumed in your current living arrangements.
What Should You Inspect Before Buying?
An inspection should address risks you cannot identify from a headline price or attractive photograph.
New Launch Checks
Review the developer’s completed projects, the unit’s specifications, its position within the site, and the contractual completion provisions. Distinguish included fittings from show-flat decoration.
Explains that developers must provide mandatory project and unit information before accepting a booking fee. Its guide also describes key collection following TOP and the relevant payment, plus a one-year defects liability period. A new home still needs inspection after handover.
Resale Checks
Visit at different times to assess traffic, light, noise and privacy. Check signs of leaks, air-conditioning condition, windows and alterations. Obtain renovation quotations before treating the asking price as affordable.
Request available management information, including maintenance contributions, sinking-fund position, meeting minutes and planned major works. The Management Corporation Strata Title (MCST) manages the development’s common property; its financial position matters as much as your unit’s condition.
Low maintenance fees alone do not prove good value. Ask whether the corporation is collecting enough funds for the building’s future needs.
Which Offers Better Rental and Resale Potential?
Neither category automatically produces better investment returns. Compare the acquisition cost, income timing, expenses, and likely exit market over the same period.
Rental Income and Holding Costs
A completed resale condo can potentially earn rent sooner, subject to possession, repairs, tenancy arrangements, and finding a tenant. An uncompleted new launch cannot generate occupancy-based rental income before it is ready for occupation and handover.
Gross rental yield is annual rent divided by purchase price, multiplied by 100. Hypothetical rent of S$4,500 monthly on a S$1.8 million property produces a 3% gross yield.
Price disclaimer: The rent and purchase price in this yield example are assumptions, not rental quotations or projected returns. Actual rent, occupancy, and costs vary.
That is not a 3% profit. Deduct maintenance, property tax, repairs, insurance, leasing costs, and vacancy to estimate operating income. Then account separately for financing and acquisition costs.
For a new launch, use several comparable rental transactions rather than one optimistic projection. Test what happens if rents are lower or several similar units seek tenants after completion.
Exit Price and Seller’s Stamp Duty
Resale liquidity means how readily you can find a buyer at an acceptable price. Evaluate the future buyer’s likely budget, competing units, layout preferences and remaining lease.
For residential property acquired on or after 4 July 2025, the standard Seller’s Stamp Duty schedule is 16%, 12%, 8% and 4% across the first four holding-year bands respectively. It is calculated on the higher of the selling price or market value, subject to applicable exemptions. No SSD is payable after four years under this schedule. Ask your lawyer to confirm the relevant acquisition and disposal dates. Avoid building an investment case around a quick resale without calculating the tax and transaction costs.
How Can You Make the Final Comparison?
Shortlist homes that meet the same essential requirements, then evaluate them using one consistent worksheet.
- Set the purpose: own stay, rental income, or a future move.
- Set the deadline: when you need possession and what waiting costs.
- Confirm affordability: cash, usable CPF, approved borrowing, and reserves.
- Compare evidence: transactions, layouts, lease details, and condition.
- Model ownership: use the same holding period and realistic expenses.
- Test the downside: lower income, repair bills, vacancy, or an earlier sale.
For own stay, give substantial weight to daily usability. For investment, prioritize net cash flow and the price a future buyer could reasonably afford. In either case, reject a property that only works if every optimistic assumption comes true.
Conclusion: Compare the Property, the Costs and Your Timeline
The new launch vs resale condo decision becomes clearer when you compare specific homes rather than labels. Newness can be valuable, but so can an established location, an inspectable unit, and earlier possession.
Choose the option that meets your needs at a sustainable total cost. Confirm transaction evidence, financing, and property details before making an offer.
Frequently Asked Questions
Is a resale condo always cheaper than a new launch?
No. Location, tenure, size, condition, and individual pricing affect the comparison. A lower PSF can still result in a higher total price if the resale unit is larger.
Is a new launch condo better for first-time buyers?
Not automatically. It may suit someone who can wait and wants new finishes. A completed resale home may better suit someone with an immediate housing need.
Does buying early guarantee capital appreciation?
No. Launch timing does not guarantee profit. Your entry price, competing supply, future demand and selling expenses determine the eventual outcome.
Can I move into a resale condo immediately?
Only when the agreed possession arrangements allow it. Check completion dates, any existing tenancy, vacant-possession terms and the time needed for renovation.
What is the most useful way to compare value?
Compare similar homes using total acquisition and holding costs, usable space, lease and location over the same ownership period. Then test whether the purchase remains affordable if circumstances change.
Singapore Property and Price Disclaimer
This article provides general information, not personalized financial, legal, or tax advice. All specific purchase prices, rents, renovation budgets, PSF figures and cost totals are hypothetical illustrations unless expressly identified otherwise. They are not Ziba Property listing quotations, valuations or guarantees. Actual prices, availability, expenses and regulations can change. Tax examples reflect the stated assumptions and rules checked on 21 September 2026.
For Singapore property transactions, consult a property agent registered with the Council for Estate Agencies (CEA) and check the agent’s registration. Consult your lawyer, lender and IRAS on contractual, financing and tax matters. CEA regulates property agencies and agents; it does not guarantee listings, prices or investment returns.
Compare Your Singapore Condo Options
Ready to compare a new launch with a completed resale home? Explore properties on Ziba Property and shortlist Singapore condos by budget, location and space. Ask the relevant agent for current availability, full costs, and possession details, then use this guide to compare each option on the same basis
About the Author
Muhammad Amir publishes Singapore-focused property content for Ziba Property. This guide draws on the official sources cited above to explain condo comparisons, ownership costs, and buying considerations. It provides educational information and does not replace advice from a CEA-registered property agent or another qualified professional.

